
The Toyota Hilux is one of the most desirable types of collateral in the Philippine lending market, so if you have one, you're holding a valuable asset. If you need money for your business, as a result of an emergency or just to have some extra cash for your work, sangla OR/CR — which involves pawning your Official Receipt and Certificate of Registration while still keeping the truck — is one of the quickest methods of accessing that value. The following guide outlines precisely what you should have ready before you go to a lender with your Hilux.
In the Philippines, pickup trucks lose less of their value than most passenger cars and the Hilux in particular retains its resale value better than almost any other vehicle in its class. When lenders and appraisers see the model — no matter if it is a Conquest, G, E, J or FX variant — they immediately recognize it, which in turn allows the valuation to be carried out more quickly and makes the financing decisions more predictable than they would be with a less common type of vehicle.
Even so, the fact that a vehicle is a good collateral option does not mean that all Hilux cars will be approved. Before giving you a loan amount, lenders still examine a number of specific details.
Across the sangla OR/CR market, a few checks come up consistently regardless of which financing company you approach:
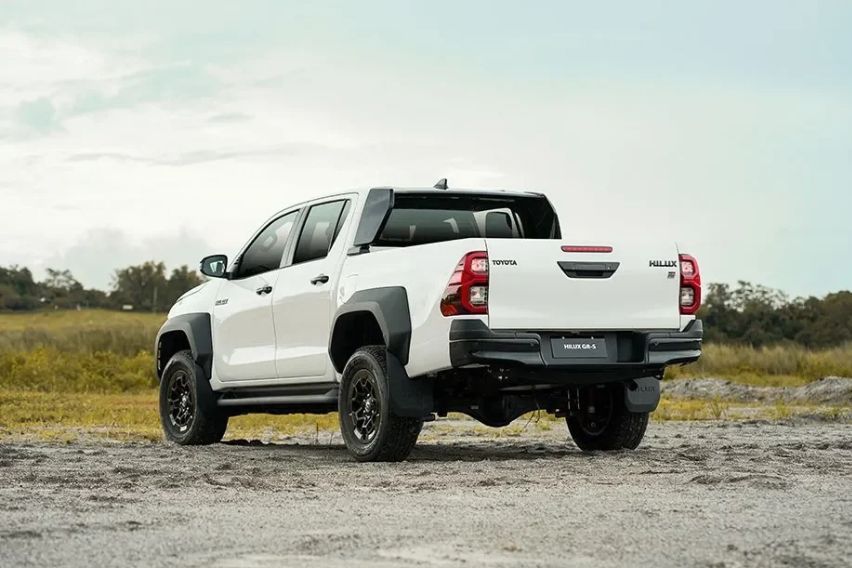 Photo from Toyota
Because the Hilux is as much a work truck as a family vehicle, a meaningful share of applicants are using it commercially — for a small business, deliveries, or as part of a fleet. If that's your situation, the paperwork lenders ask for shifts slightly, since business income and business registration documents often come into play alongside the standard personal requirements. Carmudi's refinance page lists the documents required for employed borrowers and business owners, worth checking before you apply if your Hilux does double duty for work.
Think of your "vehicle pack" as everything a loan officer needs to see in one sitting, so your application doesn't stall on missing paperwork. At minimum, expect to prepare:
Gathering all of this before you walk into a branch (or start a digital application) is the single biggest factor in getting a fast decision instead of a back-and-forth. For the full breakdown of paperwork lenders typically ask for across vehicle types, our Sangla OR/CR requirements checklist is a useful companion to this list. Once your pack is complete, you're in a strong position to find out what a lender would actually approve for your specific unit. Use your Hilux details to check pickup refinancing eligibility with Carmudi.
Almost every sangla OR/CR application includes a physical inspection of the vehicle — this is where your Hilux's condition gets translated into an actual peso figure. An appraiser will typically check the engine, chassis and body condition, tires, mileage against the odometer, and confirm the chassis/engine numbers match your OR/CR exactly. Any mismatch here is one of the most common reasons applications get delayed. You can see where the inspection fits into the overall process in Carmudi's step-by-step refinance process, which covers pickups as well as cars.
While exact figures depend on your Hilux's specific year, condition, and the lender you choose, it helps to know what a comparable Sangla OR/CR product looks like in the broader market. SB Finance's Car4Cash program, for example, offers loans up to ₱2 million against a vehicle's OR/CR, with add-on interest rates starting around 1.25% per month, repayment terms extending up to 36 months (48 months for larger loan amounts), and a processing fee of roughly 3.5% of the approved amount, plus notarial and documentary stamp fees on larger loans. Rates and ceilings vary by lender and by your Hilux's appraised value, but this gives you a realistic benchmark to compare offers against rather than going in blind.
A Toyota Hilux is genuinely one of the easier vehicles to get approved for sangla OR/CR, precisely because its resale value and recognizability work in your favor. The real variable isn't whether lenders want your Hilux as collateral — it's whether your paperwork is complete and your unit is ready for inspection on day one. Prepare the vehicle pack above, understand roughly what terms to expect, and you'll move through the process considerably faster than most applicants.
Also read: How Much Can You Borrow Against a Fully Paid Car?


